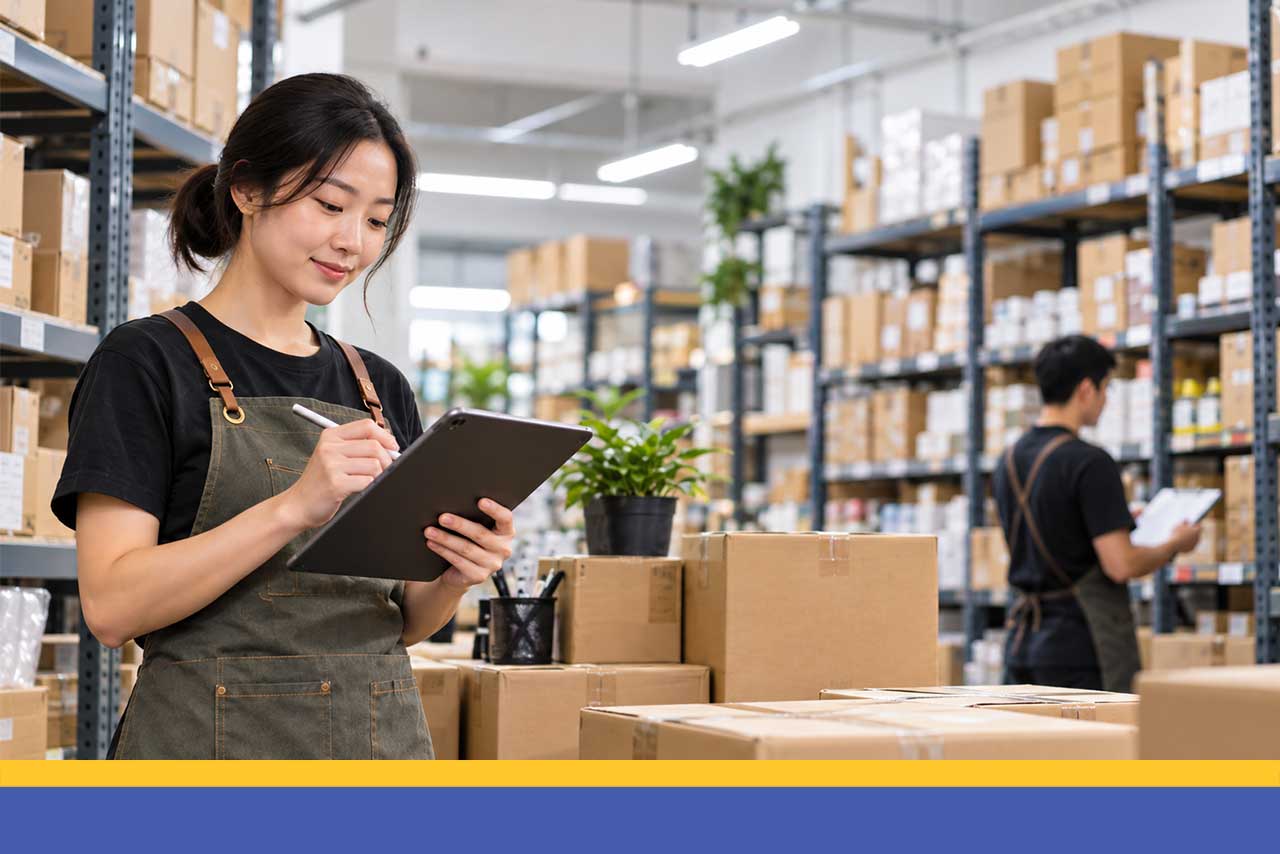
It is Sunday night. Two people are in the storeroom, one counting and one writing on a clipboard. Somebody opens a box to check what is inside and does not close it. By eleven you have a number, and by Tuesday nobody entirely trusts it, so it gets filed and the next order is placed on instinct anyway.
Almost every business does this, and almost every business finds it a waste of an evening. Not because counting is hard, but because the count is being treated as the point of the exercise. It is not. The number on its own tells you nothing you can act on.
What makes a stocktake worth doing is the difference between what you counted and what you expected. That gap is where waste, theft, receiving errors and mispriced items live, and it is the only output of the whole process that changes a decision. If you are not producing that comparison, you are not running a stocktake. You are doing an inventory, which is a much less useful thing.
Below is a step-by-step procedure that produces a usable variance, how often to run it, and what to do with what you find.
A Stocktake Is Not a Count. It Is a Comparison.
Think about what the number actually gives you. Knowing you have forty-one units of something is mildly interesting. Knowing you have forty-one when the system expected forty-eight is a finding, and it comes with a value attached, and it points at a cause.
Which means the most important part of a stocktake happens before anyone picks up a clipboard. If your expected figure does not exist, or exists but is a guess, then whatever you count cannot be compared to anything and the evening produces no information. That single point explains why so many stocktakes feel pointless, and it is entirely fixable.
What a Stocktake Looks Like When the System Is Already Counting
Every sale on QashierPOS deducts stock as it completes, so your expected position is current at all times rather than as of the last time somebody updated a spreadsheet.
On a Sunday evening, two staff members count a section each, entering figures as they go. The comparison against expected is produced immediately rather than assembled on Monday.
Most lines match. Six do not. Two are receiving errors from the same supplier, three are waste that was never recorded, and one is a product recorded under two different names by two different outlets, which is why the numbers never reconciled.
You fix the catalogue entry, change the receiving process and adjust the rest. The whole thing took ninety minutes instead of a full evening. None of that required a single manual action from you.
Step 1: Decide What You Are Counting and Why
Do not default to counting everything. A full count of an entire business is a large undertaking that most merchants can only face twice a year, which means eleven months of the year you have no idea what is happening.
Choose between a full count, which is right before a financial year end or a handover, and a cycle count, where you count a portion of your stock on a rotating schedule so everything gets counted regularly without any single evening being enormous. For most businesses a monthly cycle count on high-value and fast-moving lines, with a full count twice a year, is a better use of the same hours.
Step 2: Freeze Movement, or Account for It
Stock moving while you count it is the most common cause of a variance that is not real. A sale rung up mid-count, a delivery received into the back, a transfer sent to another outlet, and your figures are wrong before you finish.
The clean solution is counting outside trading hours, after close and before the next delivery. If that is not possible, mark a cut-off time, record anything that moves after it separately, and adjust at the end. What you must not do is count during service and hope it evens out.
Step 3: Produce Your Expected Figures First
This is the step most often skipped and the one that decides whether the exercise is worth doing. Before counting, generate the list of what your system says you should have.
If you are on a POS where each sale deducts stock, that figure already exists and is current. If your stock lives in a spreadsheet updated when someone has time, be honest that your expected figure is itself an estimate, which means any variance you find is the sum of two errors rather than one. That is worth knowing before you start, because it changes how much weight the results deserve.
Step 4: Count Blind, and Count in Pairs Where It Matters
Do not give the person counting the expected figure. If they can see that the system says forty-eight, the count will drift towards forty-eight, and not through dishonesty. It is simply how attention works when a number is already in view.
For high-value lines, have two people count independently and compare. Where they disagree, count a third time. For everything else a single blind count is enough. This one change usually improves accuracy more than any amount of extra time.
Step 5: Count by Location, Not by List
Working down a product list sends people back and forth across the premises and guarantees that something in a second location gets missed or counted twice.
Count physically instead. Finish one shelf, one fridge, one storeroom section completely before moving on, and record as you clear each area. Anything held in more than one place needs its locations named and totalled, and the golden rule is that a section is either fully counted or not started. Half-counted areas are where phantom variances come from.
Step 6: Record Into the System as You Go
Counting onto paper and typing it in later introduces a second chance to make an error, and it usually happens late at night when everyone is tired.
Enter figures directly on a device as each section is completed. If you must use paper, have one person read and another enter, that same evening, without leaving it until morning. Whatever you do, keep the raw count sheets until the variances have been investigated, because you will want to check whether a strange number was a counting error before you go looking for a cause.
Step 7: Investigate the Variances That Matter and Ignore the Rest
You will find dozens of small differences. Chasing every one of them is how stocktakes become resented.
Sort your variances by value rather than by quantity, since one missing high-value item matters more than twenty low-value ones. Then look at the top of that list only. Most findings fall into five causes: waste that was never recorded, a receiving error where you were short-delivered or over-charged, theft, a product recorded under two names, or a modifier or bundle that is not deducting components correctly.
The last two are the most common and the most overlooked, and both are catalogue problems rather than people problems.
Step 8: Adjust, Then Fix the Cause
Adjusting the system to match the count is the easy half and, on its own, useless. If you only adjust, you will find the same variance again next time and have learned nothing.
For each significant finding, name the cause and change something: a receiving check on delivery, a waste log at the end of service, a merged catalogue entry, a corrected recipe or bundle. Then note the total value of what you adjusted. That figure is what the stocktake was for, and tracking it across counts tells you whether your fixes are working.
What a Good Count Sheet Contains
Whether you use paper or a device, the sheet needs six columns and no more.
- The item name exactly as it appears in your system, so nothing has to be interpreted afterwards.
- The unit of measure, since bottles, cases and litres are where most counting confusion begins.
- The location being counted, so an item held in two places is never accidentally merged.
- The counted quantity, with space for a second count on high-value lines.
- The name of the person who counted it, which is not about blame but about who to ask.
- A notes column for anything that looked odd, because those notes usually explain your variances later.
Deliberately leave off the expected figure. Its absence is what keeps the count honest.
How Often You Should Actually Do This
The right frequency depends entirely on one thing, which is whether your expected figure maintains itself.
If your stock count only updates when someone remembers to update it, you are effectively rebuilding your inventory from scratch each time, and that needs to happen often enough to stay useful, which is exhausting and rarely sustained. If every sale deducts stock automatically, the stocktake becomes a verification rather than a reconstruction. Most businesses in that position run a monthly cycle count on their fastest and most valuable lines and a full count twice a year, and that is enough.
The hours are similar either way. The difference is whether you spend them confirming something you already know or discovering something you should have known all along.
Everything Connects, Which Is the Whole Point
A stocktake is only ever as good as the expectation it is measured against, and that expectation is produced by everything else your business does during the month.
The sale deducts the stock, so the expected figure is live. One catalogue across every outlet and channel means a product is one product, so the same item does not appear as two lines that never reconcile. Stock Request and Transfer records movements on both sides, so what left one outlet is what arrived at the other. Staff logins mean an adjustment or a void carries a name, so an unexplained variance has somewhere to be traced. Each of those is an ordinary part of trading and each one removes a category of variance before you ever pick up a clipboard.
That is why the same evening produces a finding in one business and an argument in another.
One login. One view. One platform.
Getting Started
QashierPOS, QashierHQ, QashierPay, Qashier Treats and Automated Marketing are all available to Malaysian merchants now, on one login. Your stock position updates as each sale completes, so your next stocktake starts from a figure worth comparing against.
Book a free demo and turn your next stocktake into ninety minutes instead of an evening.
Frequently Asked Questions
How do I run a stocktake?
Produce your expected figures from your system first, count outside trading hours so nothing moves, count blind and by physical location rather than down a product list, record into the system as you go, then compare counted against expected. Sort the variances by value, investigate only the largest, and fix the cause rather than just adjusting the number. The comparison is the output, not the count.
How often should a small business do a stocktake?
It depends on whether your stock figure maintains itself. If every sale deducts stock automatically, a monthly cycle count on fast-moving and high-value lines plus a full count twice a year is usually enough. If your count is maintained manually, you need to count far more often, because you are rebuilding the figure rather than verifying it.
What is the difference between a full stocktake and a cycle count?
A full stocktake counts everything at once and is best suited to a year end or a handover. A cycle count covers a portion of your stock on a rotating schedule, so everything is counted regularly without any single session being enormous. Most businesses get better results from frequent cycle counts than from two exhausting full counts a year.
Why do my stock counts never match my system?
The five usual causes are unrecorded waste, receiving errors where you were short-delivered, theft, the same product recorded under two different names, and bundles or modifiers that do not deduct their components correctly. The last two are the most common and are catalogue problems rather than people problems, so they repeat every count until the catalogue is fixed.
Should I count stock during opening hours?
Avoid it if you can, because stock moving mid-count produces variances that are not real. Count after close and before the next delivery. If you have no choice, set a cut-off time, record anything that moves afterwards separately, and adjust at the end rather than hoping it balances out.
Should the person counting see the expected figure?
No. A count drifts towards a number that is already in view, and not through dishonesty. Counting blind, with a second independent count on high-value lines, improves accuracy more than adding time to the process.
What should I do with the variances I find?
Sort them by value rather than by quantity and investigate only the top of that list. For each significant finding, name the cause and change a process, then record the total value adjusted. Tracking that figure across counts is how you tell whether your fixes are working.
Do I or my staff need an app to count stock?
No. Qashier runs in a web browser, so counts can be entered from any device without installing anything. Because stock deducts as each sale completes, the expected figure you are counting against is already current.